Case study · Digital mortgage origination
Kredi Qualify
A better first answer and a stronger mortgage pipeline
Introduction
The first screen carries a lot of weight
For lending product owners and mortgage origination leaders, the first screen of a digital journey carries a lot of weight.
If it asks for too much, prospects leave before anyone on your team knows they existed. If it asks for too little, the guidance it gives means nothing. And if it judges a household on an incomplete picture of income, it can turn away a borrower who would have qualified once the full facts were in.
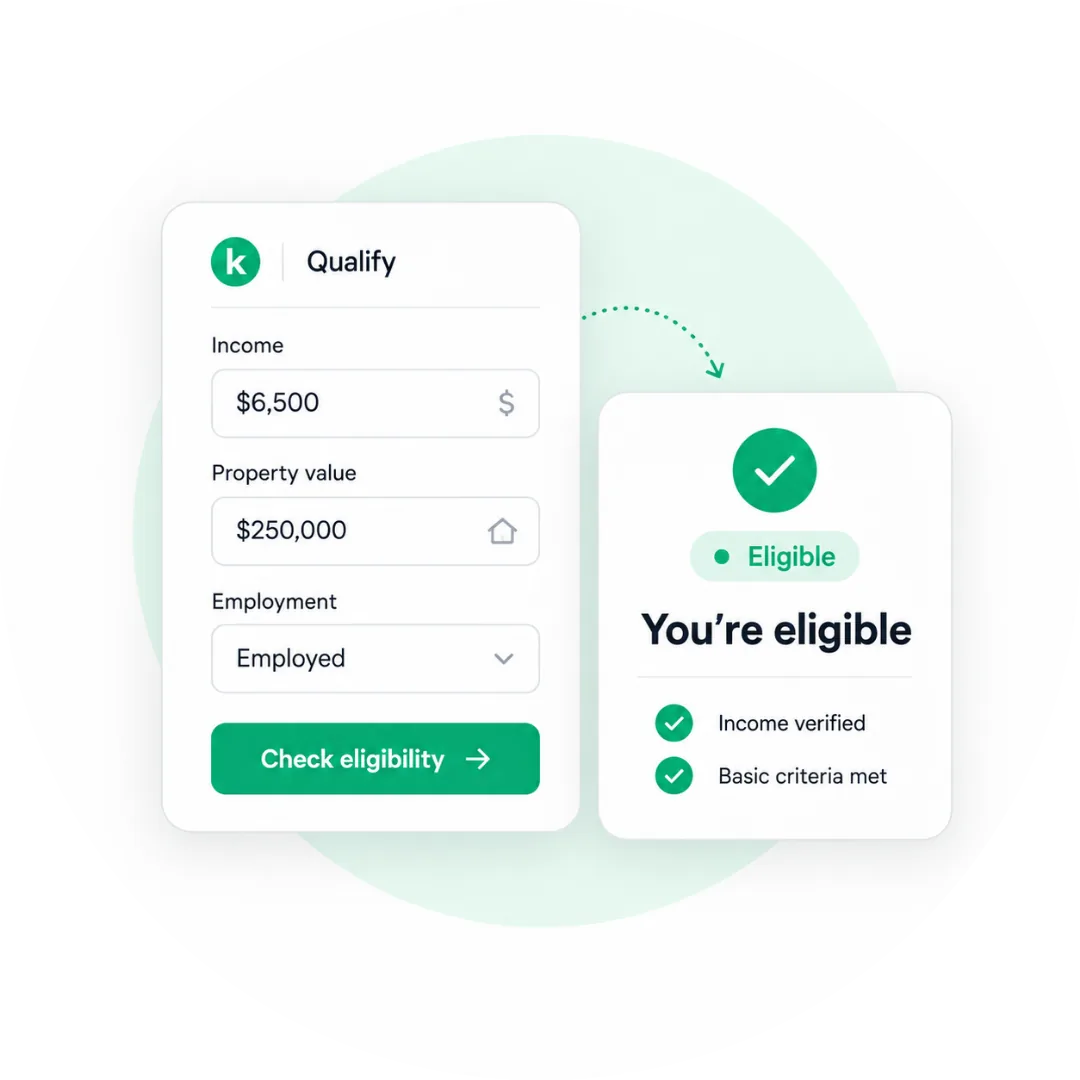
Kredi Qualify is built to manage that tension: give applicants a useful first answer and a clear next step, without trying to make the final lending decision at the front door.
Chapter 1
The challenge
Friction before the file reaches review
Chapter 1 · The challenge
Before: the traditional mortgage intake
Traditional mortgage intake provides a useful contrast to a digital-first journey. The commercial question is straightforward:
How many interested borrowers actually move forward—and how much lending opportunity is lost before the bank can review a complete file?
In the traditional reference workflow, an executive assembles the applicant’s documents into a single PDF and sends the file for internal review. Document-completeness feedback was reported to take approximately 48 hours, delaying identification of missing documents.
Waiting for human guidance, completing intake and assembling documents can add friction before a file reaches review.
Reference workflow
- 1Applicant shares documents with an executive
- 2Executive assembles a single PDF
- 3File is sent for internal review
- 4Completeness feedback arrives in ~48 hours
- !Missing documents surface late—and the borrower may stall or leave
The cost of waiting
~48 hours
to receive document-completeness feedback in the traditional reference workflow.
Every handoff creates another opportunity for a prospective borrower to stall or leave the process.
Chapter 2
The solution
A digital entry point built with Kredi Qualify
Chapter 2 · The solution
After: one connected sequence
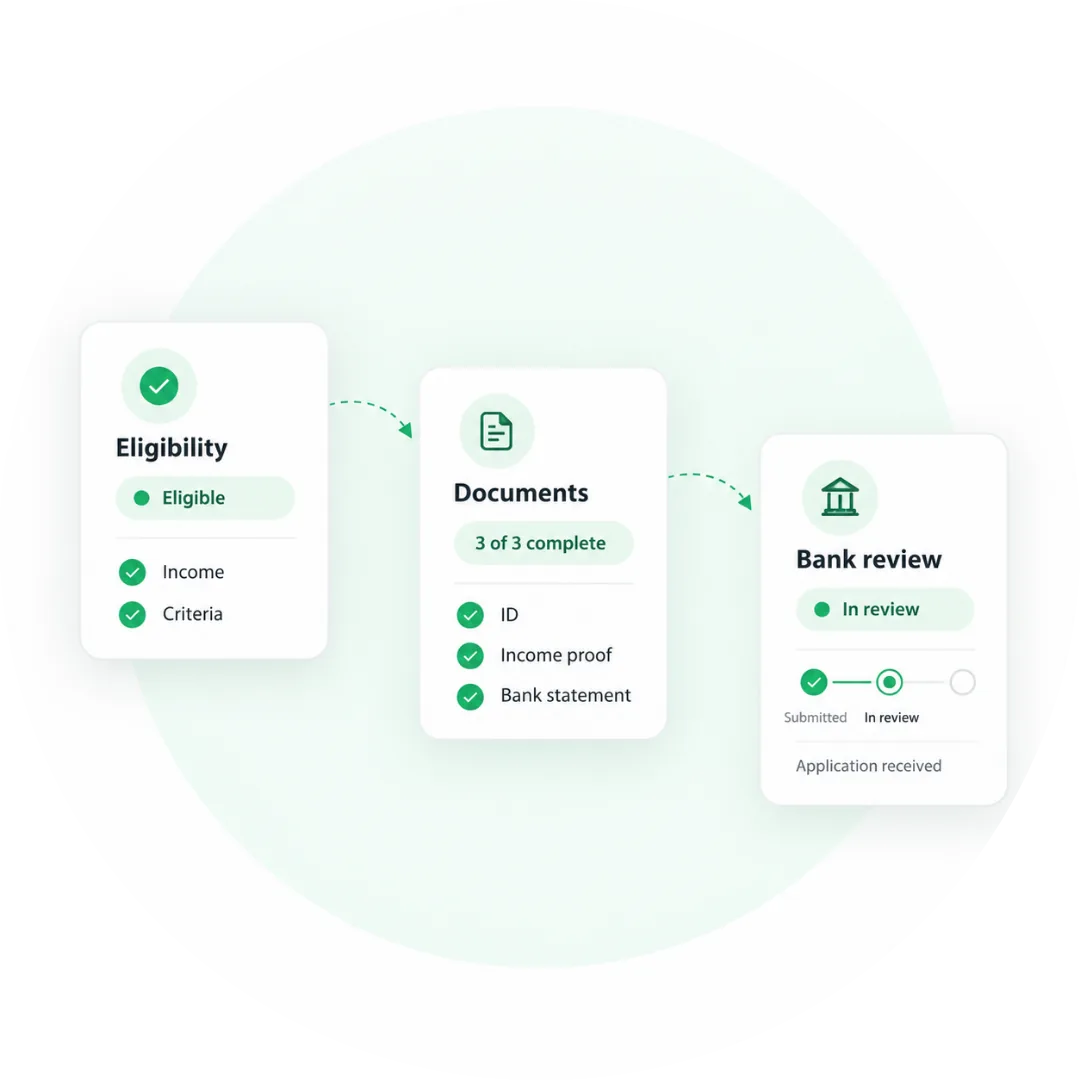
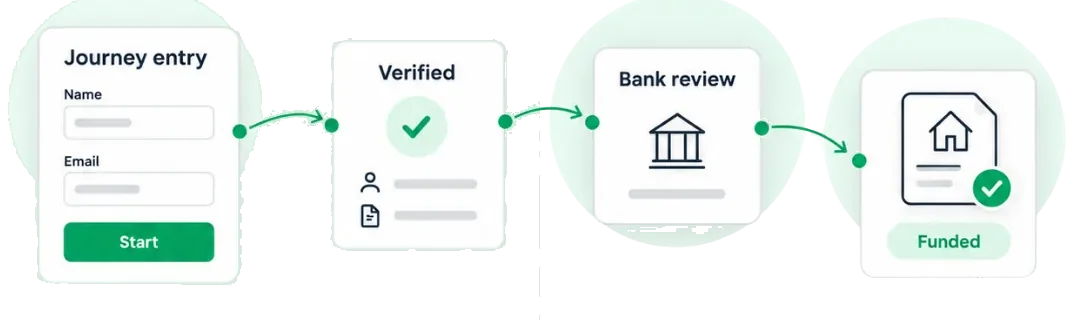
For this major Mexican retail bank launching its digital mortgage channel, Kredi built a different starting point. Kredi Qualify connects the early stages of origination in one sequence:
- 1Self-reported informationApplicants start with their own data(Kredi Qualify)
- 2Initial eligibility guidanceA useful first answer, early in the journey(Kredi Qualify)
- 3A clear next stepGuidance leads straight into action(Kredi Qualify)
- 4Initial document collectionNo separate application to start(Kredi Qualify)
- 5Bank reviewVerification downstream; final decision stays with the bank(Your bank)
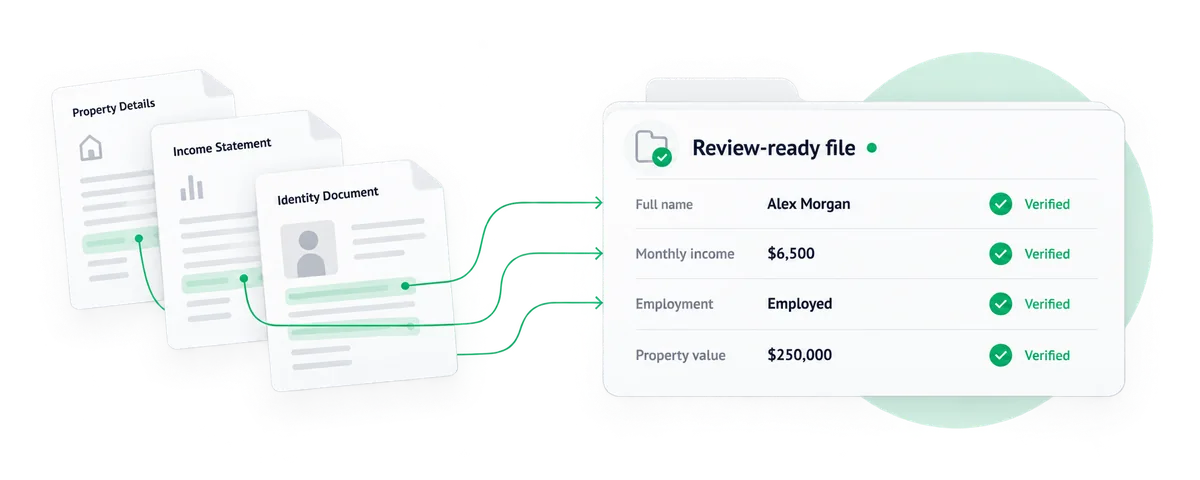
Applicants start with their own information and receive guidance about whether and how to proceed. That answer leads into document collection, rather than leaving the borrower to figure out how to start a separate application. The resulting file moves to the bank’s back-office team, framed by the information supplied at the beginning.
It is a more purposeful first interaction: enough information to guide the applicant, a practical route into the next stage, and continuity into the lender’s review process.
Chapter 2 · The solution
More lending opportunity, not just more names
A stronger entry point can support origination growth in three ways.
Keep more prospects in the journey
Reducing unnecessary effort can keep more prospects moving instead of leaving at the first screen.
Turn interest into reviewable applications
Connecting eligibility guidance to document collection helps more prospects become applications the bank can review.
Avoid losing viable borrowers
Improving the information available early helps avoid losing viable opportunities on an incomplete picture.
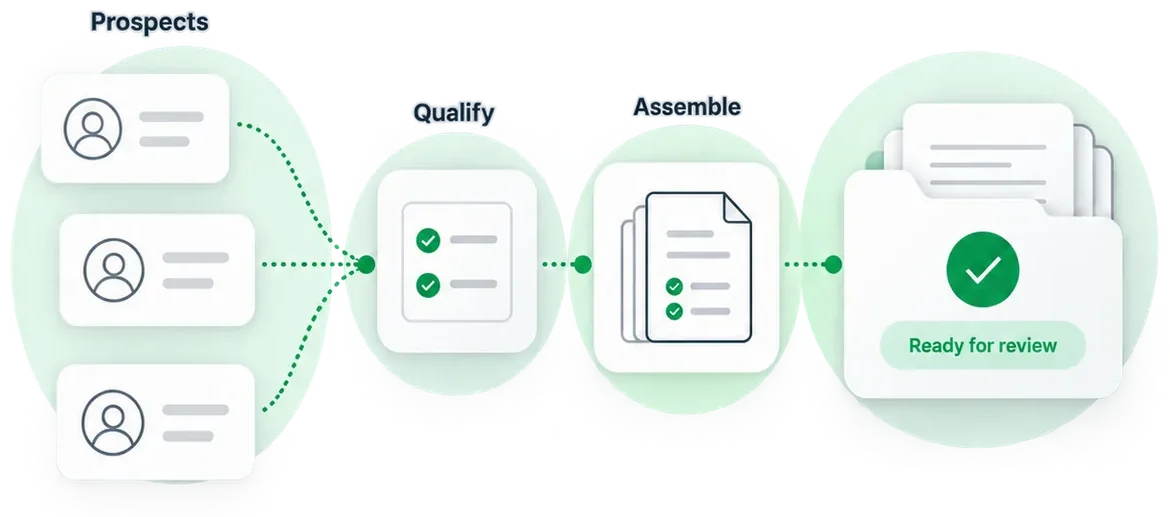
Growth comes from how many viable borrowers reach review, not from how many names enter the funnel.
Chapter 2 · The solution
Design choices that preserve opportunity
Channel design matters
A direct applicant entering information for the first time faces a different task from a broker who already holds the borrower’s data. Asking the right questions at the right stage can reduce unnecessary repetition without sacrificing useful guidance.
Household income matters
Co-borrower income handling has been part of the work to refine this bank’s journey. Considering combined income can preserve lending opportunities that an individual-income view might miss.
The objective is to preserve opportunities for verification, not loosen credit standards.
Chapter 3
The results
Measured all the way to funding
Chapter 3 · The results
A stronger beginning, measured through funding
78%
Prequalification completion
of journey entrants completed the initial step.
32%
Conversion into documentation
of applicants completing prequalification submitted the required initial documents within 7 days.
5 min
Time to initial guidance
from the start of the digital journey to delivery of the initial eligibility result.
A completed prequalification is only the first step. The business outcome is a funded mortgage.
Chapter 3 · The results
Growth the team can support
Better conversion has limited value if the team cannot handle the additional applications.
A connected intake can also create room for growth by reducing repeated screening and information requests.
What changes for the origination team
- Less repeated initial screening
- Fewer follow-up information requests
- Files framed by early applicant data
Operational capacity · Digital channel
15 min
of active staff time per applicant
1.3
follow-up contacts per file, on average.
75+
applicants supported per origination FTE per month
50%
of submitted files passed initial document-completeness review without being returned for missing or incorrect documents.
Client perspective
“We’re excited to launch a digital mortgage experience that we believe can change how home loans are delivered—making the entire process faster, more secure and easier for customers, without requiring a branch visit. We believe this can encourage more people to apply for a mortgage.”
Chapter 3 · The results
Measure success all the way to funding
- 120,000+ Journey entrants
- 78% Completed prequalification
- 32% Submitted initial documents
- 65% Review-ready files
- 12% Funded mortgages
Each conversion rate is measured against the preceding stage.
Of applications reaching the review-ready stage, 12% progressed to funding. Median entry-to-funding time among funded mortgages was 45 days.
These are outcomes of the broader origination process. Qualify contributes at the front end; acquisition mix, underwriting, pricing, borrower follow-through and closing also influence the result.
A stronger mortgage pipeline
A better first answer builds a stronger pipeline
For credit unions, community banks and other mortgage lenders, the commercial case is clear: help more viable borrowers take the next step, give the bank more review-ready opportunities, and connect that progress to actual funded lending.
A better first answer matters when it builds a stronger mortgage pipeline, not merely a longer prospect list.
Let’s talk about your origination journey
Eduardo Barrientos · eduardo.barrientos@kredi.dev